
 See My Latest Article on HelloNation
Homeowners insurance can cover many forms of storm and disaster damage, but it does not cover every natural hazard automatically. For households in Cape Girardeau, MO, the most important distinction is between covered events such as windstorms and tornadoes, and commonly excluded events such as flooding and earthquake damage.
The answer depends on the cause of the loss, the policy language, the deductible, and whether separate coverage or an endorsement was purchased.
Which natural disasters are usually covered?
Standard homeowners insurance generally covers direct damage caused by listed or included perils such as fire, lightning, windstorm, hail, and the weight of ice or snow. In Missouri, this commonly means a policy may respond to damage from tornado winds, severe thunderstorms, fallen trees, hail, or lightning when the policy’s conditions are met. ([insurance.mo.gov](https://insurance.mo.gov/consumer-faqs/homeowners-insurance-faqs?utm_source=openai))
Examples may include:
- Wind tearing shingles from a roof
- Hail breaking siding or damaging roofing materials
- A tree falling on the home during a severe storm
- Lightning causing a fire or damaging covered electrical components
- A covered loss making the home temporarily unlivable
Coverage may apply to more than the building itself. A homeowners policy commonly includes protection for the dwelling, personal belongings, detached structures such as a shed or fence, personal liability, and additional living expenses when a covered loss prevents the household from living at home. The exact limits and exclusions appear in the policy declarations and forms. ([content.naic.org](https://content.naic.org/consumer/homeowners-insurance.htm?utm_source=openai))
Does homeowners insurance cover tornado damage?
Usually, yes, if the damage is caused by wind or another covered peril and the policy does not contain a specific exclusion. Tornado claims may involve damage to roofs, siding, windows, garages, personal property, and landscaping features.
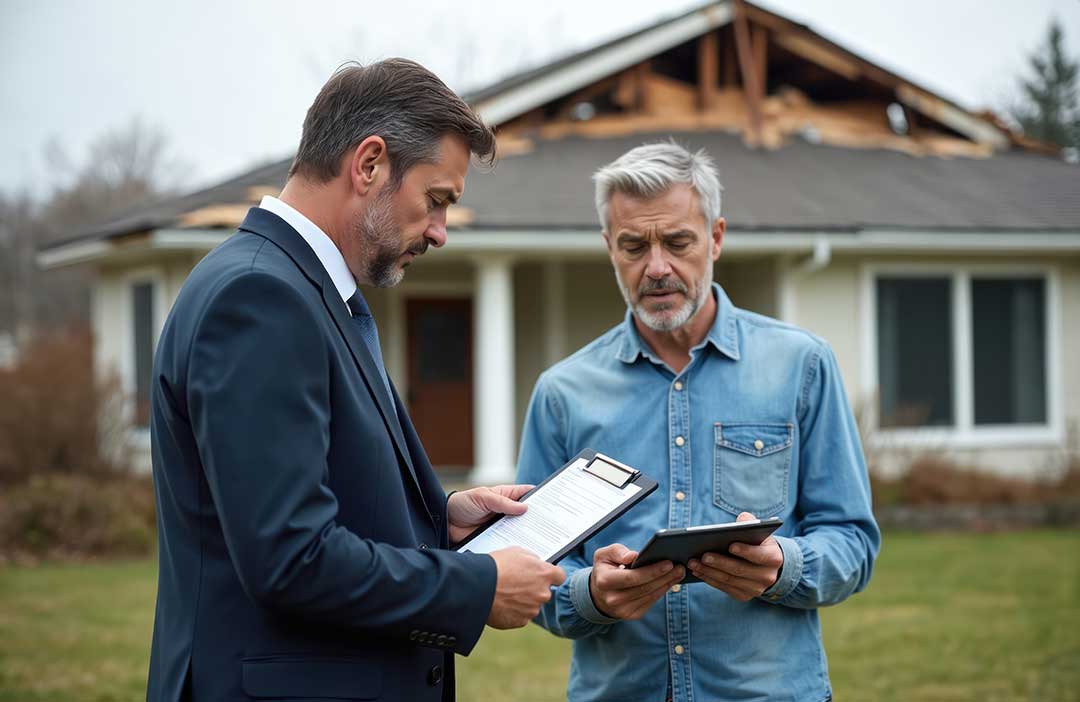
A claim can become more complicated when damage results from multiple causes. For example, wind may open a section of the roof, and rain may then enter through that opening. The insurer may review whether the wind-created opening and resulting interior damage are covered, whether the property was properly maintained, and whether any exclusions apply.
Wind or hail deductibles may also be different from the standard deductible. A policy might use a fixed dollar deductible, while another may apply a percentage based on the insured value of the home. The declarations page should show which deductible applies to a particular loss.
Does homeowners insurance cover flood damage?
Generally, no. Standard homeowners insurance usually excludes flood damage, including water that rises from heavy rain, overflowing waterways, storm surge, or surface runoff. Missouri’s Department of Insurance advises that flood coverage must generally be purchased separately through a flood insurance policy or other available arrangement. ([insurance.mo.gov](https://insurance.mo.gov/consumer-faqs/homeowners-insurance-faqs?utm_source=openai))
Flooding can occur even when a property is not immediately beside a river or other body of water. Heavy rainfall, drainage problems, saturated ground, and fast-moving runoff can all contribute to water entering a home. For that reason, a household should not rely only on whether the property is shown in a high-risk flood area.
Flood insurance typically has its own limits, deductibles, exclusions, and waiting-period rules. Missouri insurance guidance notes that a newly purchased policy may not take effect immediately, so waiting until severe weather is approaching can leave a coverage gap. ([insurance.mo.gov](https://insurance.mo.gov/insurance-news/prepare-now-potential-flooding-insurance-coverage?utm_source=openai))
Water damage is not always classified as flooding. A burst interior pipe, roof leak caused by a covered event, or sudden plumbing failure may be treated differently from water entering from outside. The source and pathway of the water usually matter.
Does homeowners insurance cover earthquakes?
A standard homeowners policy generally does not cover direct earthquake damage. Earthquake protection may be available as an endorsement or as a separate policy, but its terms can differ substantially from ordinary homeowners coverage. ([insurance.mo.gov](https://insurance.mo.gov/earthquake-insurance?utm_source=openai))
Earthquake insurance often has a percentage deductible rather than a fixed dollar amount. A 10% deductible on a $300,000 insured dwelling limit could mean the first $30,000 of covered dwelling damage is the homeowner’s responsibility. Contents may have a separate deductible or separate limits.
The cause of damage also matters. Earthquake insurance may address shaking and ground movement, while a standard homeowners policy may cover a resulting fire under its fire coverage. Flooding that follows an earthquake generally requires flood coverage rather than earthquake coverage. ([insurance.mo.gov](https://insurance.mo.gov/earthquake-insurance?utm_source=openai))
This distinction is relevant for Missouri households because earthquake risk exists in the broader region, even though earthquakes are less familiar than tornadoes or severe thunderstorms.
What about sewer backup, sump pumps, and mudslides?
These losses are often misunderstood because they may involve water but are not necessarily considered flood damage.
Sewer or drain backup may be excluded from a standard policy unless backup coverage was added. Damage caused by a failed sump pump may also require specific coverage. A policy may cover sudden water damage from a covered plumbing failure while excluding water that enters through a drain, sewer, or sump system.
Mudflow and landslide coverage can be especially limited. Earth movement exclusions may apply even when heavy rain contributes to the event. Because these losses are highly dependent on policy wording, the exclusions and endorsements should be reviewed before severe weather occurs.
What does a deductible mean after a disaster?
A deductible is the amount the homeowner pays before insurance contributes to a covered claim. It may apply separately to the dwelling and personal property, or a single deductible may apply depending on the policy structure.
After a major storm, homeowners should confirm:
- The standard deductible
- Any wind, hail, named-storm, or earthquake deductible
- Whether the deductible is a dollar amount or percentage
- Whether separate deductibles apply to buildings and belongings
- Whether the policy pays replacement cost or actual cash value
Replacement cost generally focuses on repairing or replacing property without subtracting ordinary depreciation, subject to policy terms and limits. Actual cash value subtracts depreciation. A roof, appliance, or older piece of furniture may have a significantly lower actual cash value than the cost of buying a new replacement.
What should residents do after storm or disaster damage?
Safety comes first. Avoid damaged structures, exposed wiring, unstable trees, and standing water that may conceal hazards. Reasonable temporary measures, such as covering a broken window or placing a tarp over an opening, can help prevent additional damage when it is safe to do so.
Documentation is also useful. Take photographs and videos before making permanent repairs, keep receipts for temporary expenses, and make a list of damaged belongings. Do not discard damaged property unless it creates a health or safety risk or the insurer gives permission.
A home inventory prepared before a loss can make it easier to identify missing or damaged possessions. Missouri insurance officials also recommend maintaining records, securing loose outdoor items, clearing gutters, and addressing deteriorated roofing or siding before severe weather. ([insurance.mo.gov](https://insurance.mo.gov/insurance-news/missouri-department-commerce-and-insurance-offers-guidance-missourians-impacted-1?utm_source=openai))
The most reliable answer for any particular disaster is found in the policy’s declarations page, coverage forms, exclusions, and endorsements. A homeowners policy may provide strong protection against wind, hail, fire, and related losses while leaving separate gaps for flood, earthquake, sewer backup, or other specialized risks.